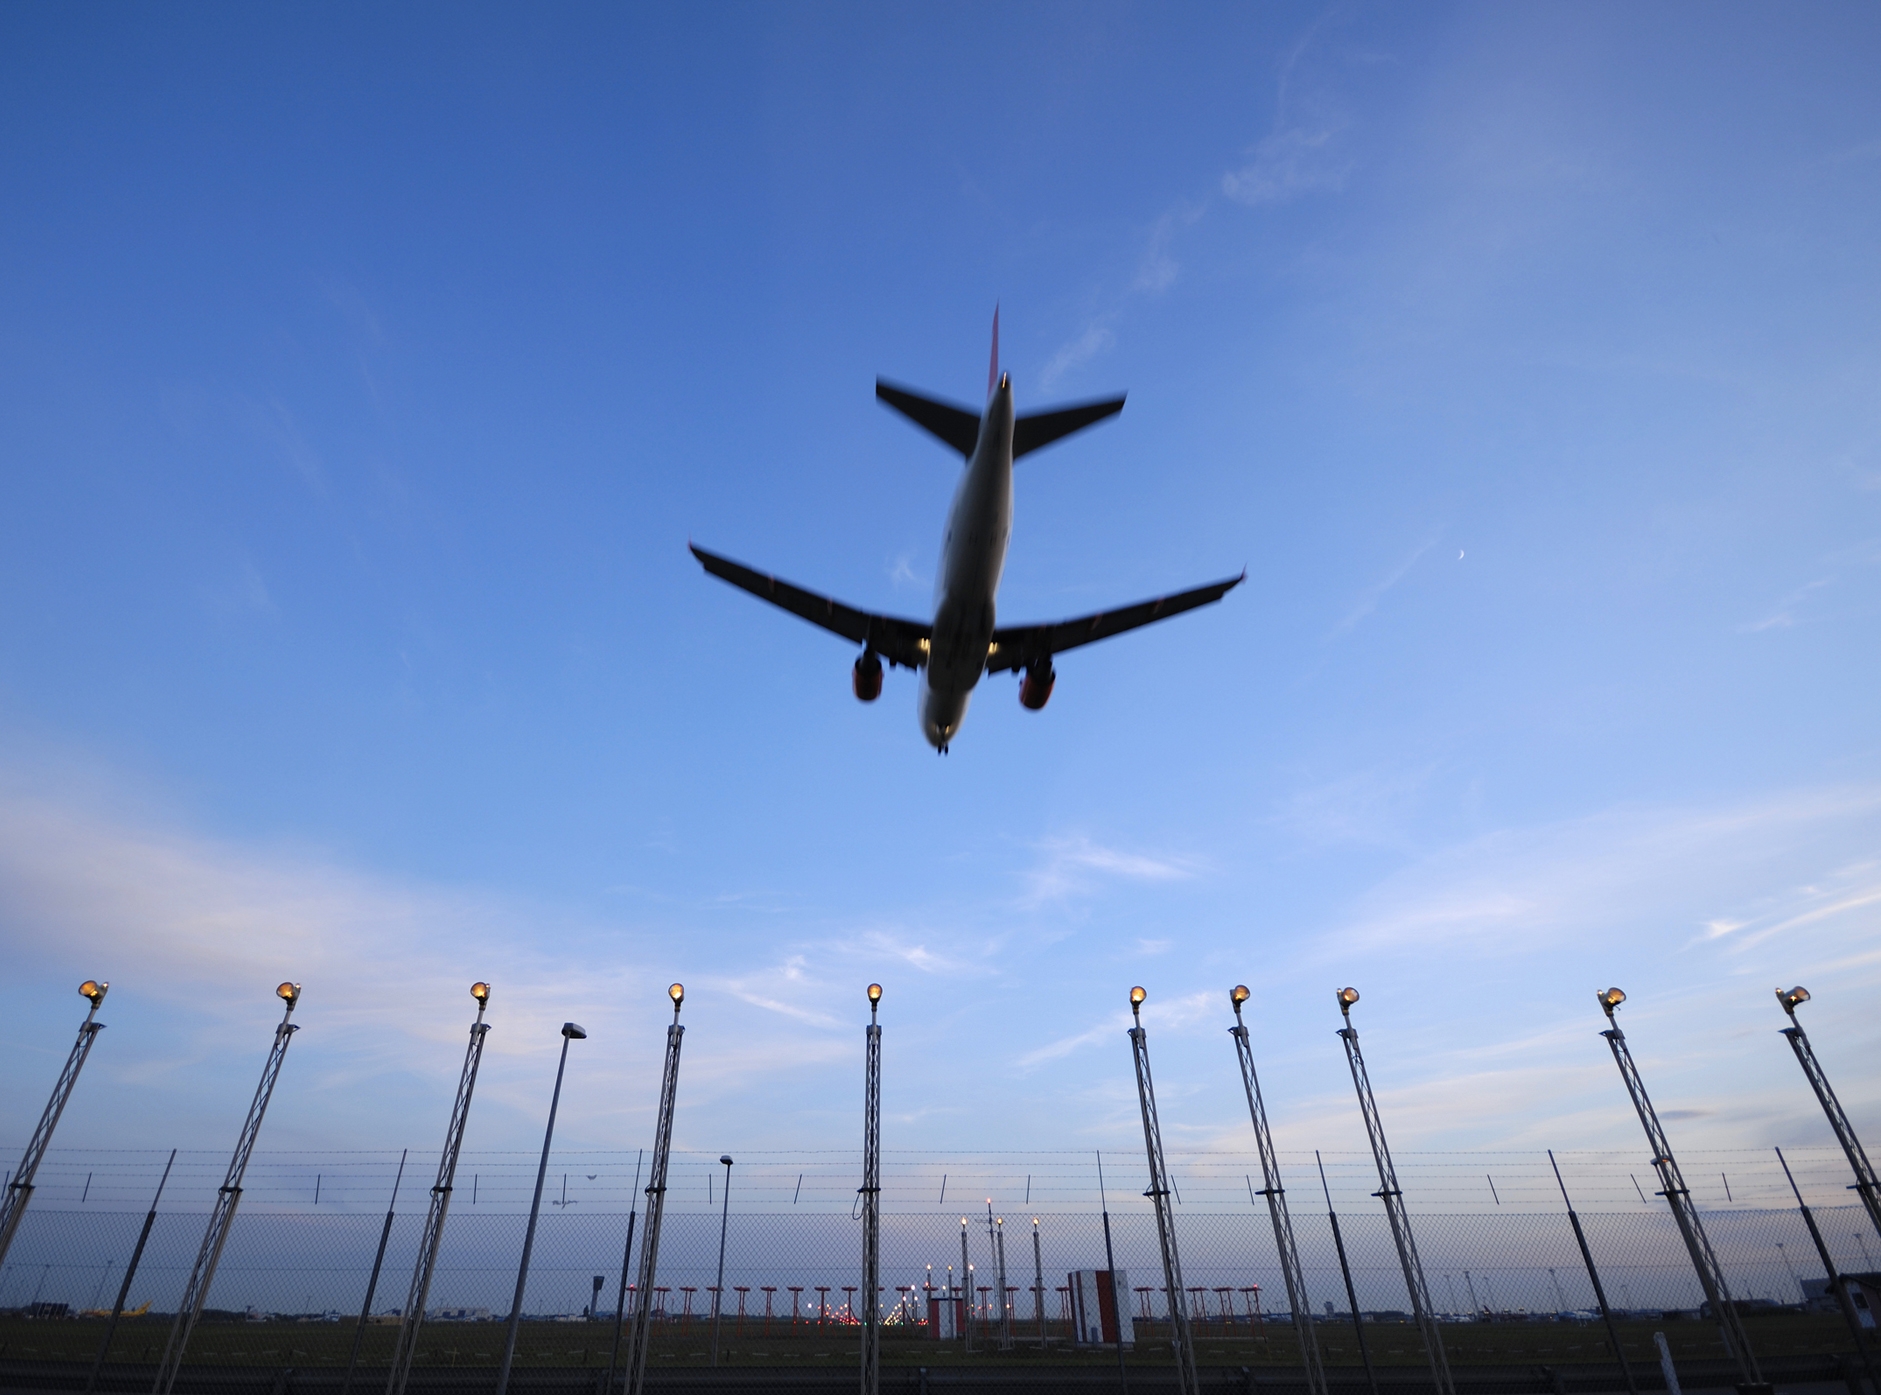
The broker WH Ireland repeated its buy ‘advice’ and 206p price target on aircraft leasing firm Avation (LON:AVAP), which has just completed the acquisition of an Airbus A320-200 on lease to Air France.
The broker pointed out that on a 0.8 times net book value and 5.5 times forward earnings, Avation is valued at a significant discount to its peers.
Yet, as WHI points out, none of its peers has Avation’s “growth trajectory”.
“We anticipate further aircraft acquisitions being made as the group deploys the capital it raised from the US$100m bond issue in May 2015,” analyst Ian Berry said.
“We anticipate Avation will continue to execute its aggressive growth strategy, growing revenue, earnings and net assets whilst also lowering its cost of capital and reducing its customer risk profile by adding new airlines.”
At 8.50, the shares were 1% higher at 137.5p each.
Few infrastructure projects have the potential to reshape an island's future quite like the ongoing transformation of Nevis Airport. To gain deeper insight into this ambitious development and the...
The U.S. Federal Aviation Administration has certified the Boeing 737-10, the newest and largest member of the 737 MAX family, paving the way for Boeing [NYSE: BA] to begin customer deliveri...
Asco, a subsidiary of Montana Aerospace AG, achieves significant technological milestone in the development of a hybrid multi-material Rear Secondary Structure for Airbus. Montana Aerospace,...
The Tennessee Valley Authority is demonstrating the real-world value of the Tecnam P2012 Special Mission Platform (SMP), which has become a vital tool for monitoring and maintaining its...